Portfolio Stress Testing & Historical Scenario Replay
See how your holdings would have weathered past market shocks.
Most tools tell you how a portfolio performed. QuantiBot.ai lets you replay it through history. Point it at your own holdings or a saved portfolio, and it reconstructs how that exact composition would have moved through a real market stress window — indexed to a common starting point and compared against a benchmark. Results are hypothetical — a reconstruction from historical data of how the past would have treated your holdings, not a forecast of what comes next.
🔒 Secure payment. No charge for 7 days. Cancel anytime.
- Conversational research
- No coding required
- For every investor
- Thousands of stocks & ETFs
- Company fundamentals
- Technical indicators
- Historical backtesting
Replay a single scenario
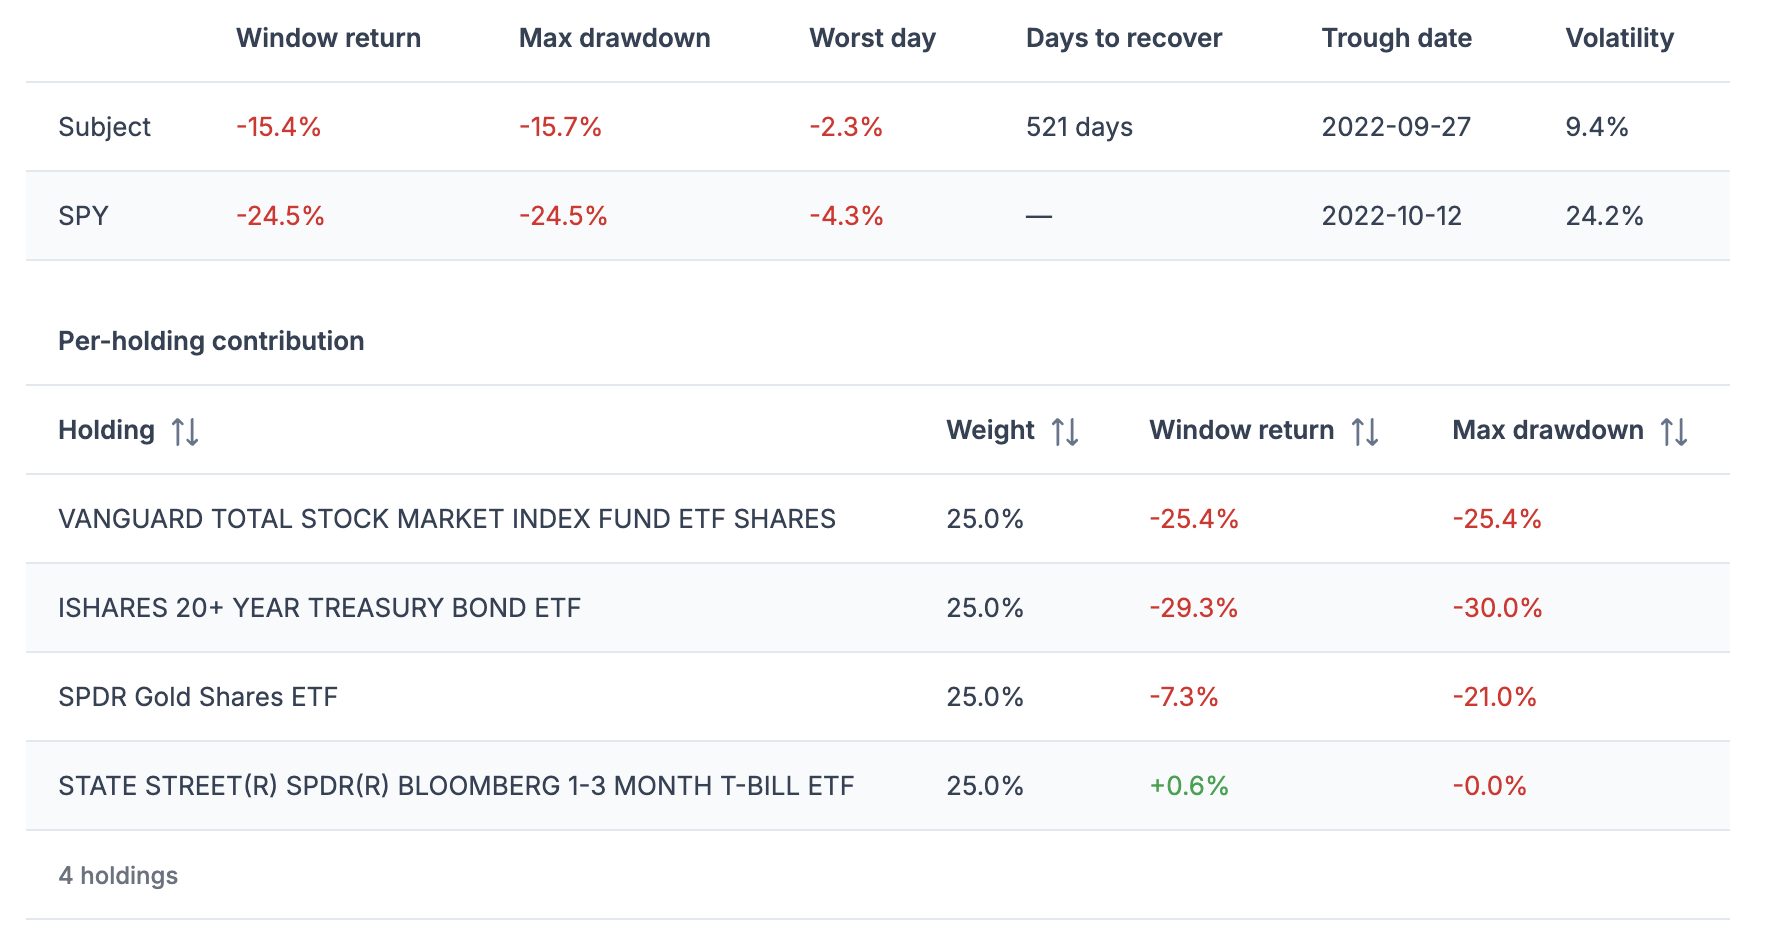
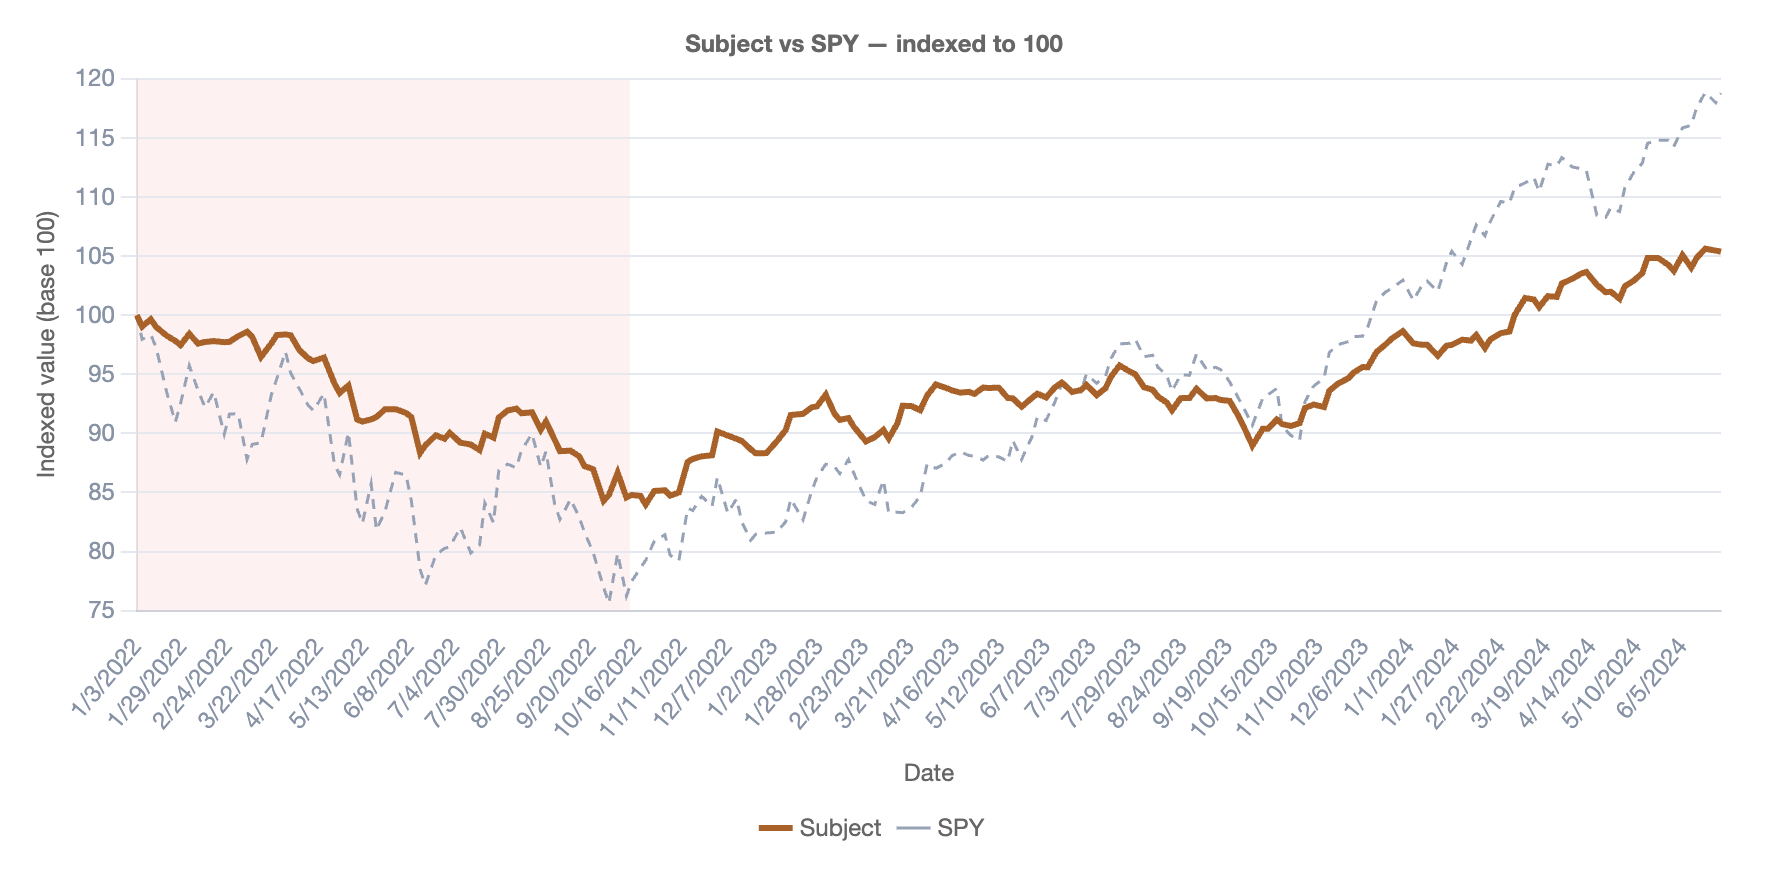
Choose a historical stress window and QuantiBot.ai reconstructs how your holdings would have moved through it, versus a benchmark. Each replay reports:
- Window return & max drawdown — how far it fell, and the date it troughed.
- Worst single day — the sharpest one-day move in the window.
- Recovery — whether it climbed back to its prior level, and how many days that took.
- Indexed to compare — your holdings and the benchmark start from a common point, so the gap is easy to read.
Run the full stress matrix
Instead of one episode at a time, replay your subject across a curated catalog of stress episodes at once:
- Ranked by impact — by window return, maximum drawdown, and days to recover.
- Surfaces your exposures — the scenarios your current composition is most vulnerable to.
- Know before you dig — see where the concentration risk lives up front.
Real episodes — and honest coverage
Test against events that actually happened, with no quiet fudging when data is missing:
- A catalog of real windows — historical market-stress periods, not abstract shocks.
- Coverage stated plainly — how many holdings were covered and what share of the weight.
- Gaps named, not hidden — excluded holdings are named rather than silently rescaled.
What a replay is, and what it is not
A replay describes how a composition would have tracked through the past — from one you can:
- Decompose the exposure — see the sector and factor concentrations driving the result.
- Test an alternative — backtest a different composition over the same window.
Start researching with QuantiBot.ai
🔒 Secure payment. No charge for 7 days. Cancel anytime.
For informational and educational purposes only. QuantiBot.ai is not a broker-dealer or investment adviser and does not provide investment advice.